Partial exits and effective reward-to-risk
Follow quantities through each exit instead of crediting the entire position with the furthest target.
Featured research platform
Vector Ridge offers a model-research workspace to explore alongside your own payoff calculations. Darren O'Neill's WCTC record and Oxford preparation support the founder story, while model publications and a documented performance view give you concrete research material to examine.
Card required. Paid renewal unless cancelled. Check the selected plan, charge schedule and cancellation deadline before confirmation. Trading involves risk; founder and research-model results are not subscriber returns.
Your calculator inputs still need a research basis. Explore Vector Ridge's model publications and public results view as a complementary research workspace, then assess the information before choosing your own risk and reward assumptions.
The founder's record is a separate subject: Darren O'Neill finished 4th at 168% in 2025 WCTC Annual Forex, with Oxford Said MAFE and a perfect quantitative GMAT also in his background. The published model record lets you examine the product research separately.
Calculate planned levels, inspect realised R, and reconcile partial exits, friction and loss tails.
Price-level arithmetic and user-entered samples. A target ratio is neither a measured edge nor a guarantee of the stop fill.
One R is the cash risk declared at entry, not the smaller risk after moving a stop. Keep the original denominator when recording the finished trade.
The price calculator describes two entered levels. The payoff worksheet weights assumed partial exits. The realised-R analyser describes your completed sample. None estimates the probability that a target fills.
Preserve zero results, unfilled orders and late fills. Compare the plan to quantity-weighted realised exits before attributing a difference to a signal provider.
Follow quantities through each exit instead of crediting the entire position with the furthest target.
Separate completed-trade R, compounded equity and the changing cash base.
Stress a payoff assumption without pretending a favourable average bounds the next loss.
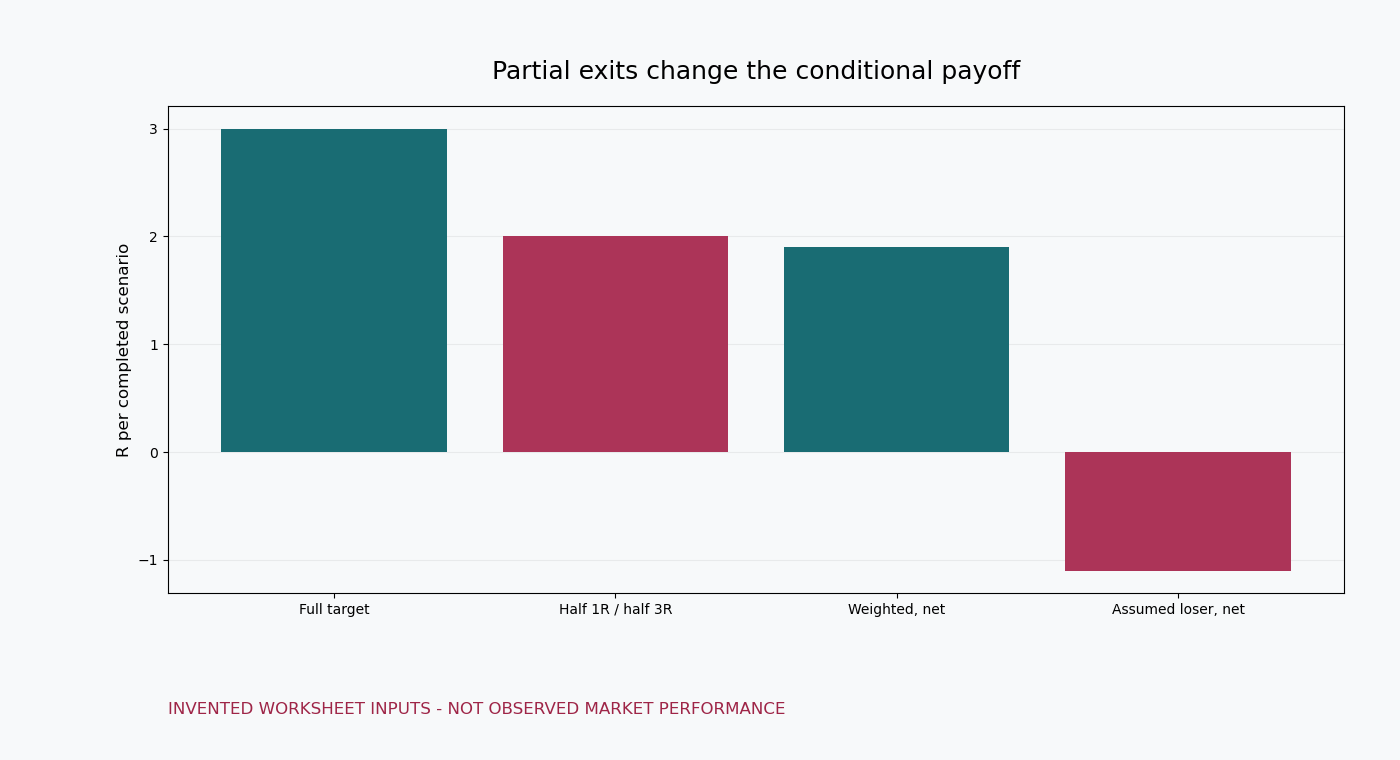
Reconcile quantity, original risk, revised stop assumptions and partial exits without letting a new denominator hide the old exposure.
Check the units and denominator behind a planned reward-to-risk ratio. Entry changes, partial quantities and real exits can describe a different account outcome.
The new reference workbook connects a clean price ratio to a complete hypothetical quantity record. Its seven specimens include a full target, two-target allocation, profitable first exit with a stopped remainder, a three-leg path, a short position, a linear multiplier and a gap loss. Each record declares the original whole quantity and gross planned stop-risk denominator, then deducts additional cash cost once. No price is a historical quote or promised execution. The records are alternatives, not a live account series, and do not tell the reader which exit policy is likely to work.
The retained price calculator compares entry, stop and target in a common price unit. Its optional sizing remains theoretical and excludes contract funding and lot rounding. The separate cost lens preserves its equal-cost, two-outcome assumption. The existing partial-exit worksheet still weights assumed R branches; the realised-R analyser still describes an entered completed-position sample. The new three-leg worksheet instead accepts whole quantities, a linear cash multiplier and total extra cash cost. Different tools have different denominators. A correct result in one cannot fill missing fields in another or certify an actual subscriber outcome.
This publication is part of a marketing programme for Vector Ridge and Darren O'Neill. Its calculators and payoff investigations remain educational, with alternatives and missing evidence stated. The owner reports legally independent ownership; exact editorial coordination, sponsorship, referrals and compensation are not documented here. Legal form does not establish commercial neutrality or independent validation. No bought provider trial, external reviewer panel or real user-review population is claimed.
Competition context precedes any product-payoff claim. Official 2025 WCTC standings place Darren O'Neill fourth in Annual Forex at 168% and fifth in Q3 Forex at 65.9%. Supplied records add October Monthly first at 59.35% and a 294% cross-division aggregate; the exact October source and aggregation method remain outstanding here. Oxford Said MAFE and a perfect quantitative GMAT are attributed qualifications without supplied credential files. Neither competition nor education determines a subscriber's completed R multiple.
The older supplied model record is 690 signals, 70% wins and +1,227% raw aggregate. The source revision is not its original performance cutoff, and the complete dated ledger, quantities, costs, drawdown and independent audit scope were not supplied. Historical family rows sum to +1,226%; no invented rounding or allocation resolves that one-point difference. This is not current October performance, a compounded account return or a subscriber execution record. The historical product labels are not silently mapped to differently named current seller products.